At WiT Singapore last October, Filip Filipov, COO (now CEO) of OAG, opened his presentation with a provocation and a timer: 80 slides in 900 seconds. The pace mattered. Travel has entered its vertical-line decade, he argued – a period where technology cycles compress, incumbents retool faster than startups, and the boundaries between shopping, booking, payment and in-trip operations collapse into a single, delegated action.
But before looking forward, he rewound 20 years. In 2005, the year WiT was born, the world looked vastly different. Online travel penetration hovered under 20%. The biggest travel company by revenue was American Express. Booking hotels involved unintuitive forms and slow search results, and flight search was essentially airport-to-airport date matching. The idea that strangers would pay to sleep in someone’s house was laughable. Uber did not exist. TikTok did not exist. And mobile phones were not the primary interface for travel.
Fast-forward to today: 5.4 billion internet users, over 70% online penetration in travel, mobile replacing desktop as the dominant medium, and payment systems rewriting the economics of how travel transacts. “The biggest company in travel is Google,” Filipov quipped, not because it takes bookings, but because it sends the demand that drives them.
The last 20 years, he argued, were defined by five structural shifts: online, mobile, payments, new supply, and scale. Airbnb, Uber, Kiwi.com, Ctrip/Trip.com, Klook and others expanded what “travel supply” meant, and bookings platforms aggregated fragmentation into something navigable. M&A was relentless; the companies that survived either acquired or were acquired.
Then came AI and the growth curves went asymmetrical. ChatGPT reached 100 million users in two months; a new AI platform scaled from USD 1 million to USD 500 million ARR in 17 months. Adoption curves that previously took a decade became a quarter. “Money is flowing, stakes are rising,” Filipov said. “Buckle up – this is going to get faster.”
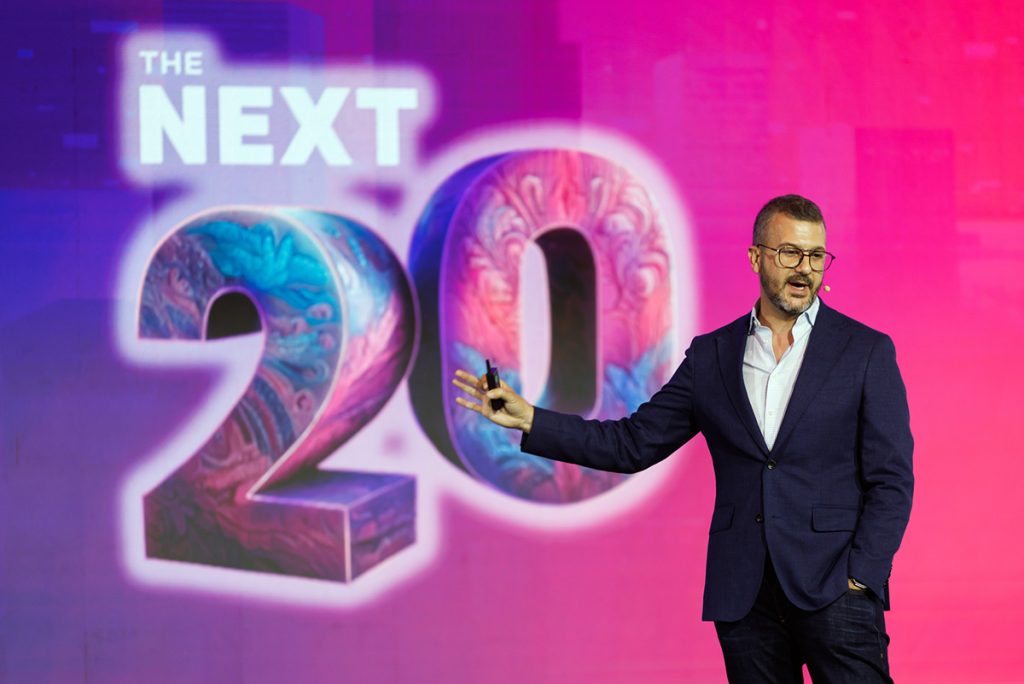
So what does the next 20 years look like? Instead of predicting what will change, he inverted the question: what will not? Out of those constants, he drew 10 big bets.
-
Travel Will Still Be Stressful
Disruption is a structural feature: airport queues, IRROPs, paperwork, timing anxiety, cross-border rules, missed connections. The bet isn’t that stress disappears – it’s that intelligent agents will increasingly pre-empt it. Think rebooking before the delay hits, baggage reconciliation without the counter, and proactive visa or insurance logic executed in-flight. The agent becomes a buffer, not a brochure.
-
People Will Still Prefer Lower Prices for the Same Quality
Price sensitivity is timeless. The deal changes, however: personalization finally works because AI has context beyond cookies – patterns, constraints, preferences, tolerance for risk, loyalty signals, and dynamic intent. Comparison doesn’t go away; it gets individualized.
-
Control Will Remain With the Traveller
Delegation does not mean automation without consent. Even the most agentic AI will not “book everything for me” without a final checkpoint. Humans want ownership over the last mile — whether to confirm, override, or reject. Trust comes from agency, not abdication.
-
Laziness Is a Feature, Not a Flaw
Nobody wants to plan for two and a half hours across 19 tabs for a three-day trip. Efficiency is a consumer demand signal. The future collapses the funnel: inspiration → planning → booking → payment → in-trip → post-trip feedback happen through continuous context, not discrete hand-offs.
-
We Still Crave a Little Magic
Optimizing for efficiency alone is sterile. Travellers want a dose of serendipity, novelty and discovery – the off-beat coffee shop, the local farm, the neighbourhood gallery, or the village hike. AI becomes not just a recommender, but a curator. Inspiration isn’t dead; it just needs better UX.
-
Travel Supply Will Stay Fragmented
Fragmentation is travel’s defining characteristic, not an inconvenience. With 900+ airlines, millions of lodging types, and an explosion of tours & experiences, the job of aggregators remains essential. What changes is the unit: instead of selling components (flight, room, attraction), the new frontier is stitching the itinerary into a single coherent journey — commercially, operationally and emotionally.
-
Infrastructure Will Never Keep Up With Demand
Technology scales faster than airports, airspace and immigration systems. Asia and the Middle East invest aggressively; Europe lags. Capacity constraints become strategic choke points. The unlock isn’t just more concrete — it’s more intelligence: forecasting, dynamic gate allocation, predictive ATC, baggage automation, and intermodal planning. Supply is finite; optimization is infinite.
-
The Invisible Hand Will Guide Demand to New Frontiers
“70% of travellers go to 44% of the places,” Filipov noted. Overtourism compresses experience value and breaks the promise of travel. AI will re-route demand toward second cities and hidden gems not because it is ideological, but because it is utility-driven. If Tokyo is saturated, Matsumoto becomes the alternative; if Bali hits peak load, Flores becomes the relief valve. The algorithm becomes the redistributor.
-
Trust Remains the Currency of Travel
Travel requires trust across three layers: the provider, the payment, and increasingly, the agent. Trust is earned through repetition and lost through a single failure. The agent that consistently delivers – rebooks, refunds, recommends and reconciles without friction – becomes the default. Loyalty evolves from points to proof.
-
It Always Takes Believers to Re-Imagine Travel
Every cycle is driven by outsiders who try the impossible: founders, operators, product leaders and investors who don’t accept constraints. Airbnb, Booking, Trip.com, Skyscanner, Wego, Klook – the list is long and still growing. But for the next cycle, Filipov makes an unexpected contrarian bet: the incumbents will lead. They have distribution, aggregation, capital, and now access to the same AI primitives once reserved for startups. The garage is no longer the only place where velocity lives.
From Consumers to Systems
His framing pushes the industry’s imagination beyond UX and into architecture: payments, identity, multimodal logistics, data synchronization, capacity management and predictive operations. Asia features prominently – mobile-first behaviour, wallet adoption, superapps, OTA scale, and a cultural willingness to experiment.
Why It Matters
The constants tell us what jobs-to-be-done remain unsolved: reduce stress, redistribute demand, optimize infrastructure, collapse friction, increase trust, and curate delight. Travel’s next decade isn’t just about selling more, it’s about orchestrating better.
If the last 20 years were about getting travel online, the next 20 will be about getting travel synchronized.
Watch the full presentation here: