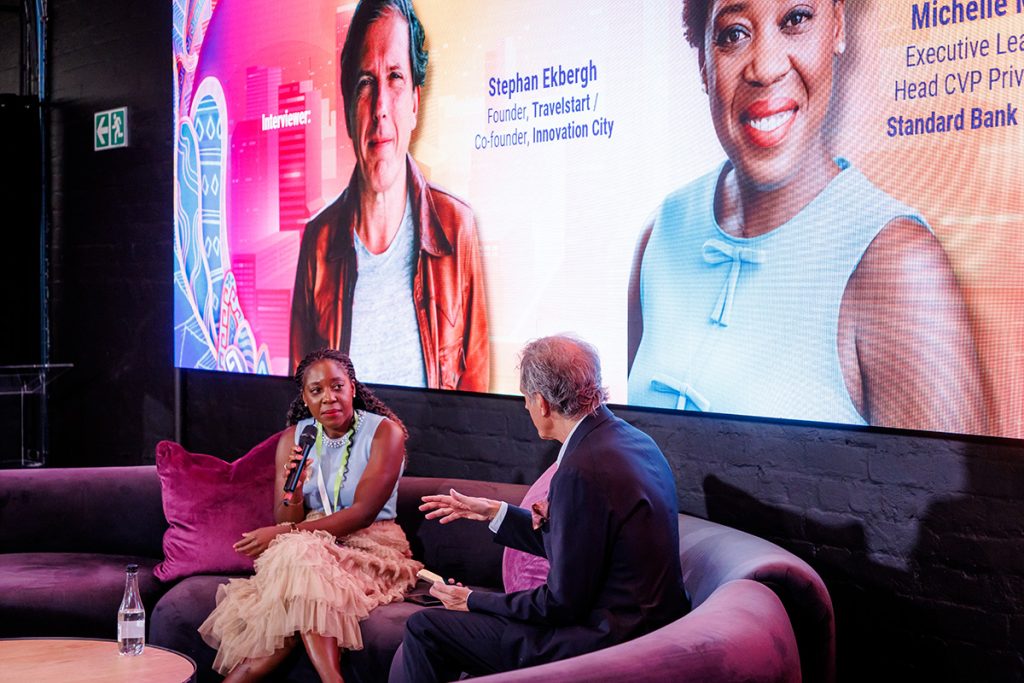
When Stephan Ekbergh, the Swedish-born founder of Travelstart, compares South African banks to those in his homeland, the verdict is blunt: “When I go back to Sweden, I feel like I’m moving back to the Middle Ages.”
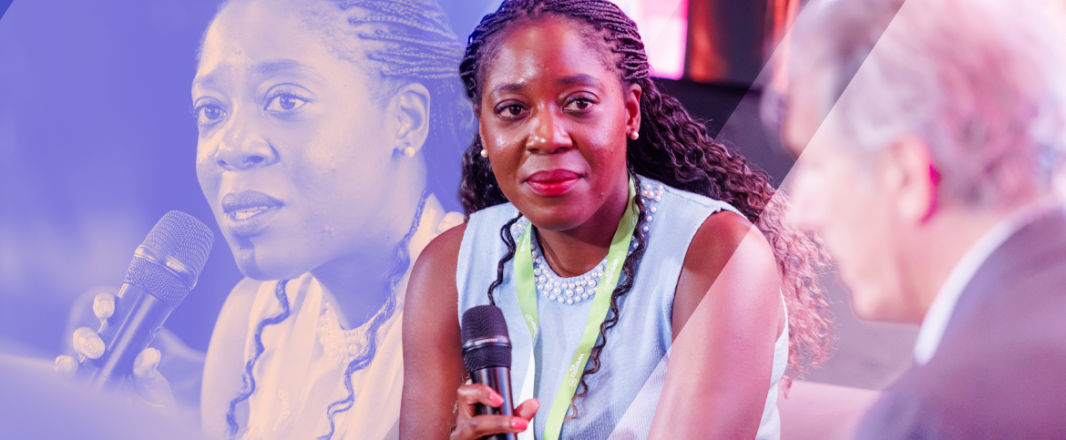
And Michelle Munemo, Standard Bank’s Executive Lead for Travel and Head of CVP Private Banking SA, had the perfect rebuttal during their coffee chat at WiT Africa – South Africa’s financial innovation, she argues, wasn’t born out of abundance, it was born out of necessity.
“A lot of the infrastructure and structural challenges in South Africa have been key drivers to the innovations we’ve seen,” Munemo explained. Mobile banking took hold not because it was trendy, but because it was the most effective way to scale financial services across a complex, unequal landscape. The same logic extends across the continent. Kenya’s M-Pesa. Nigeria’s fintech boom.
“We’ve just developed this resilience,” Munemo said. “And you’ll see a lot of really interesting things coming out of the African continent because of the challenges that we have.”
The Private Banking Paradox
Understanding why travel has become a central pillar of Standard Bank’s strategy requires understanding who their private banking clients actually are and how different they look from their global counterparts.
Globally, private banking clients are typically defined by a net asset value exceeding US$1 million. In South Africa, the threshold is an annual income of around R600,000. The result is a uniquely challenging segment: clients with the expectations of wealthy international banking customers, but without the asset base to match.
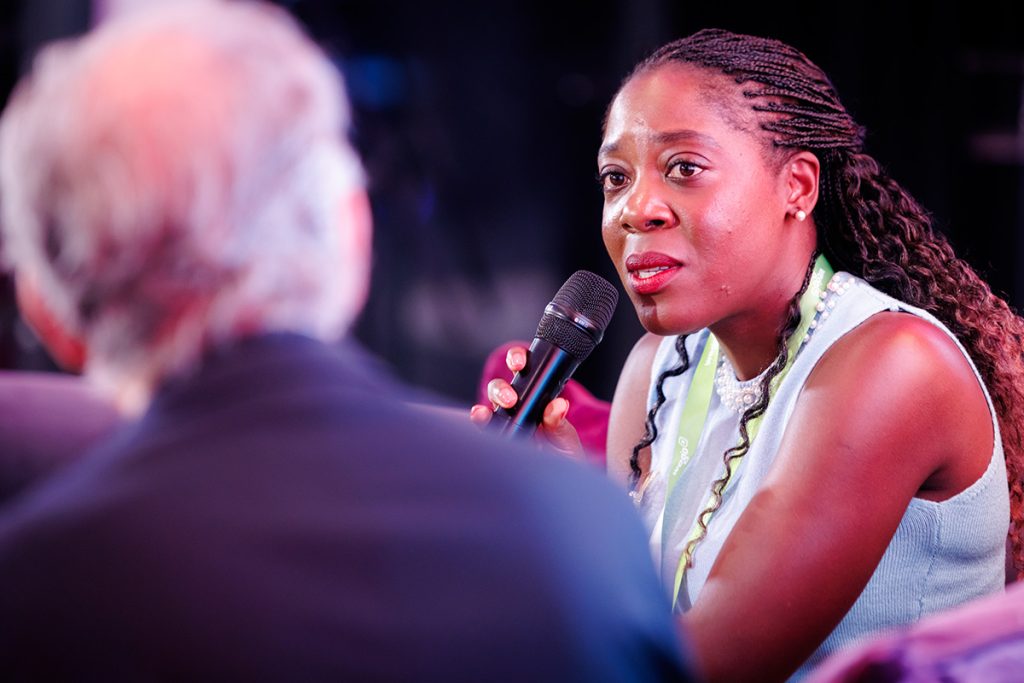
“That is a very difficult client to solve for,” Munemo said, gesturing to illustrate her point. “Their needs are here, but their magnitude is not here.”
Compounding the challenge is a sobering macro reality. Despite some improvement in South Africa’s overall economic picture, approximately 40% of credit-active South Africans are in default on their credit obligations. The macro story and the household story are telling very different tales and it’s at the household level where banks must compete.
Why travel? Why now?
With GDP growth rates languishing below 2% for years, there’s no flood of new, high-earning clients entering the market. Every major South African bank is chasing the same customer base. The result, as Munemo describes it, is a country of multi-banked consumers – people who maintain accounts at multiple institutions, extracting benefits from each.
“A bank account is a bank account is a bank account, wherever you go,” she said. “What’s becoming really important from a differentiation perspective is starting to engage that client on their lifestyle.”
And in South Africa, travel is a lifestyle marker. The ability to travel, especially internationally, is considered a visible signal of affluence. Standard Bank could see this in the data: clients were spending heavily on travel, but spreading that spend across multiple institutions.
“We see it as a key lever to retain our clients, as well as to grow our client base,” Munemo said.
The bank launched its flights platform in November of last year, built on a discount model. But what surprised them was telling: some clients booked through the platform even when they didn’t qualify for a discount. “That says a client wants trust, they want safety, and they want convenience,” Munemo noted.
Trust as the killer app
Ekbergh interjected, “You trust the bank with your money, now they’re going to trust you with spending the money too.” Munemo confirmed it without hesitation.
For Standard Bank, the travel proposition was never purely about margin. Yes, the income statement matters. But it’s trust – the same trust that makes someone hand over their salary, their savings, their mortgage – that is transferable. When a client books a flight through their bank, they’re not just making a transaction. They’re deepening a relationship.
This also explains why Standard Bank is deliberately avoiding the race to the bottom on price. Pure discounting, Munemo warned, is a dangerous game – smart consumers will simply chase the cheapest deal across whichever platform offers it, with no loyalty attached. “You will lack the depth and engagement,” she said, “which is where travel actually becomes a key lever for us.”
Instead, Standard Bank has designed around behavioural loyalty. Everyday card spend – fuel, groceries, routine purchases – unlocks higher travel discounts. The goal is not a one-time booking. It’s an ongoing relationship between the client’s financial behaviour and their travel ambitions.
Knowing the customer: Segments that matter
Munemo identified three distinct segments driving Standard Bank’s travel strategy:
Older, affluent clients represent significant value. They have more disposable income and more time – a combination that translates directly into travel spend and frequency.
Family travellers reflect a uniquely South African reality. Some 60% of South Africans prefer to travel in family groups, and Standard Bank has structured its proposition around this. Book eight times on the platform, and up to eight family members can access the discounts, a differentiated offering that doesn’t yet exist widely in the market.
HENRYs (High Earners, Not Rich Yet) – present the greatest challenge and the greatest opportunity. Numbering around one million in South Africa, this younger, aspirational segment views travel as aspirational but lacks the disposable income to pursue it freely. They are also notoriously fickle with their loyalty. “You really need to think about how you engage them in deeper loyalty rather than a one-to-one transaction,” Munemo said.
A collaborator, not a competitor
Ekbergh acknowledged, with some good humour, that there is grumbling in the traditional travel trade – OTAs and agents watching as banks absorb a growing share of travel transactions. Munemo’s response was measured, but clear.
“Banks are certainly not looking to become an OTA or a travel agent,” she said. “OTAs have a very important role, as do aggregators, as do other technology players within the travel industry.”
Standard Bank cannot build a full travel proposition alone – it relies on partners like Travelstart. The opportunity, she argued, lies in simplifying how these players work together to serve the same client. “There is enough room in the playground for everyone.”
The AI horizon
With seconds left in their session, Ekbergh couldn’t resist: “We haven’t spoken of AI once. How about that?”
Munemo outlined two fronts. Internally, Standard Bank is exploring AI to accelerate development and drive cost efficiencies, including AI-assisted coding, which she noted mirrors a trend visible across the industry.
But it’s the customer-facing application that excites her most. Hyper-personalisation. AI-driven travel planning. Recommendations built on the rich, deep transactional data that a primary bank holds on its clients. “We see that you travel to Europe every summer,” she said. “We should be speaking to you about that in January.”
The line between being helpful and being intrusive is thin. Munemo is clear about which side Standard Bank intends to be on. “Personalisation,” she said, with a smile, “not being more freaky.”