According to CarTrawler’s 2014 Ancillary Revenue Yearbook, ancillary revenues by the top 10 airlines last year were US$21.4 billion. The Americas took the lion share of this, comfortably over 50% at US$13.2 billion and transacting at a higher spend rate of $26 per passenger.
In comparison, Europe and Russia had a combined spend of US$5.1 billion, at US$24 per passenger and APAC was a US$3.1 billion total spend with a lower US$13 per passenger spend rate. Examination of the figures shows that the lower spend is driven by the differences in the APAC region where there is less resale of Frequent Flyer miles, but no less instance of the sale of ancillaries.
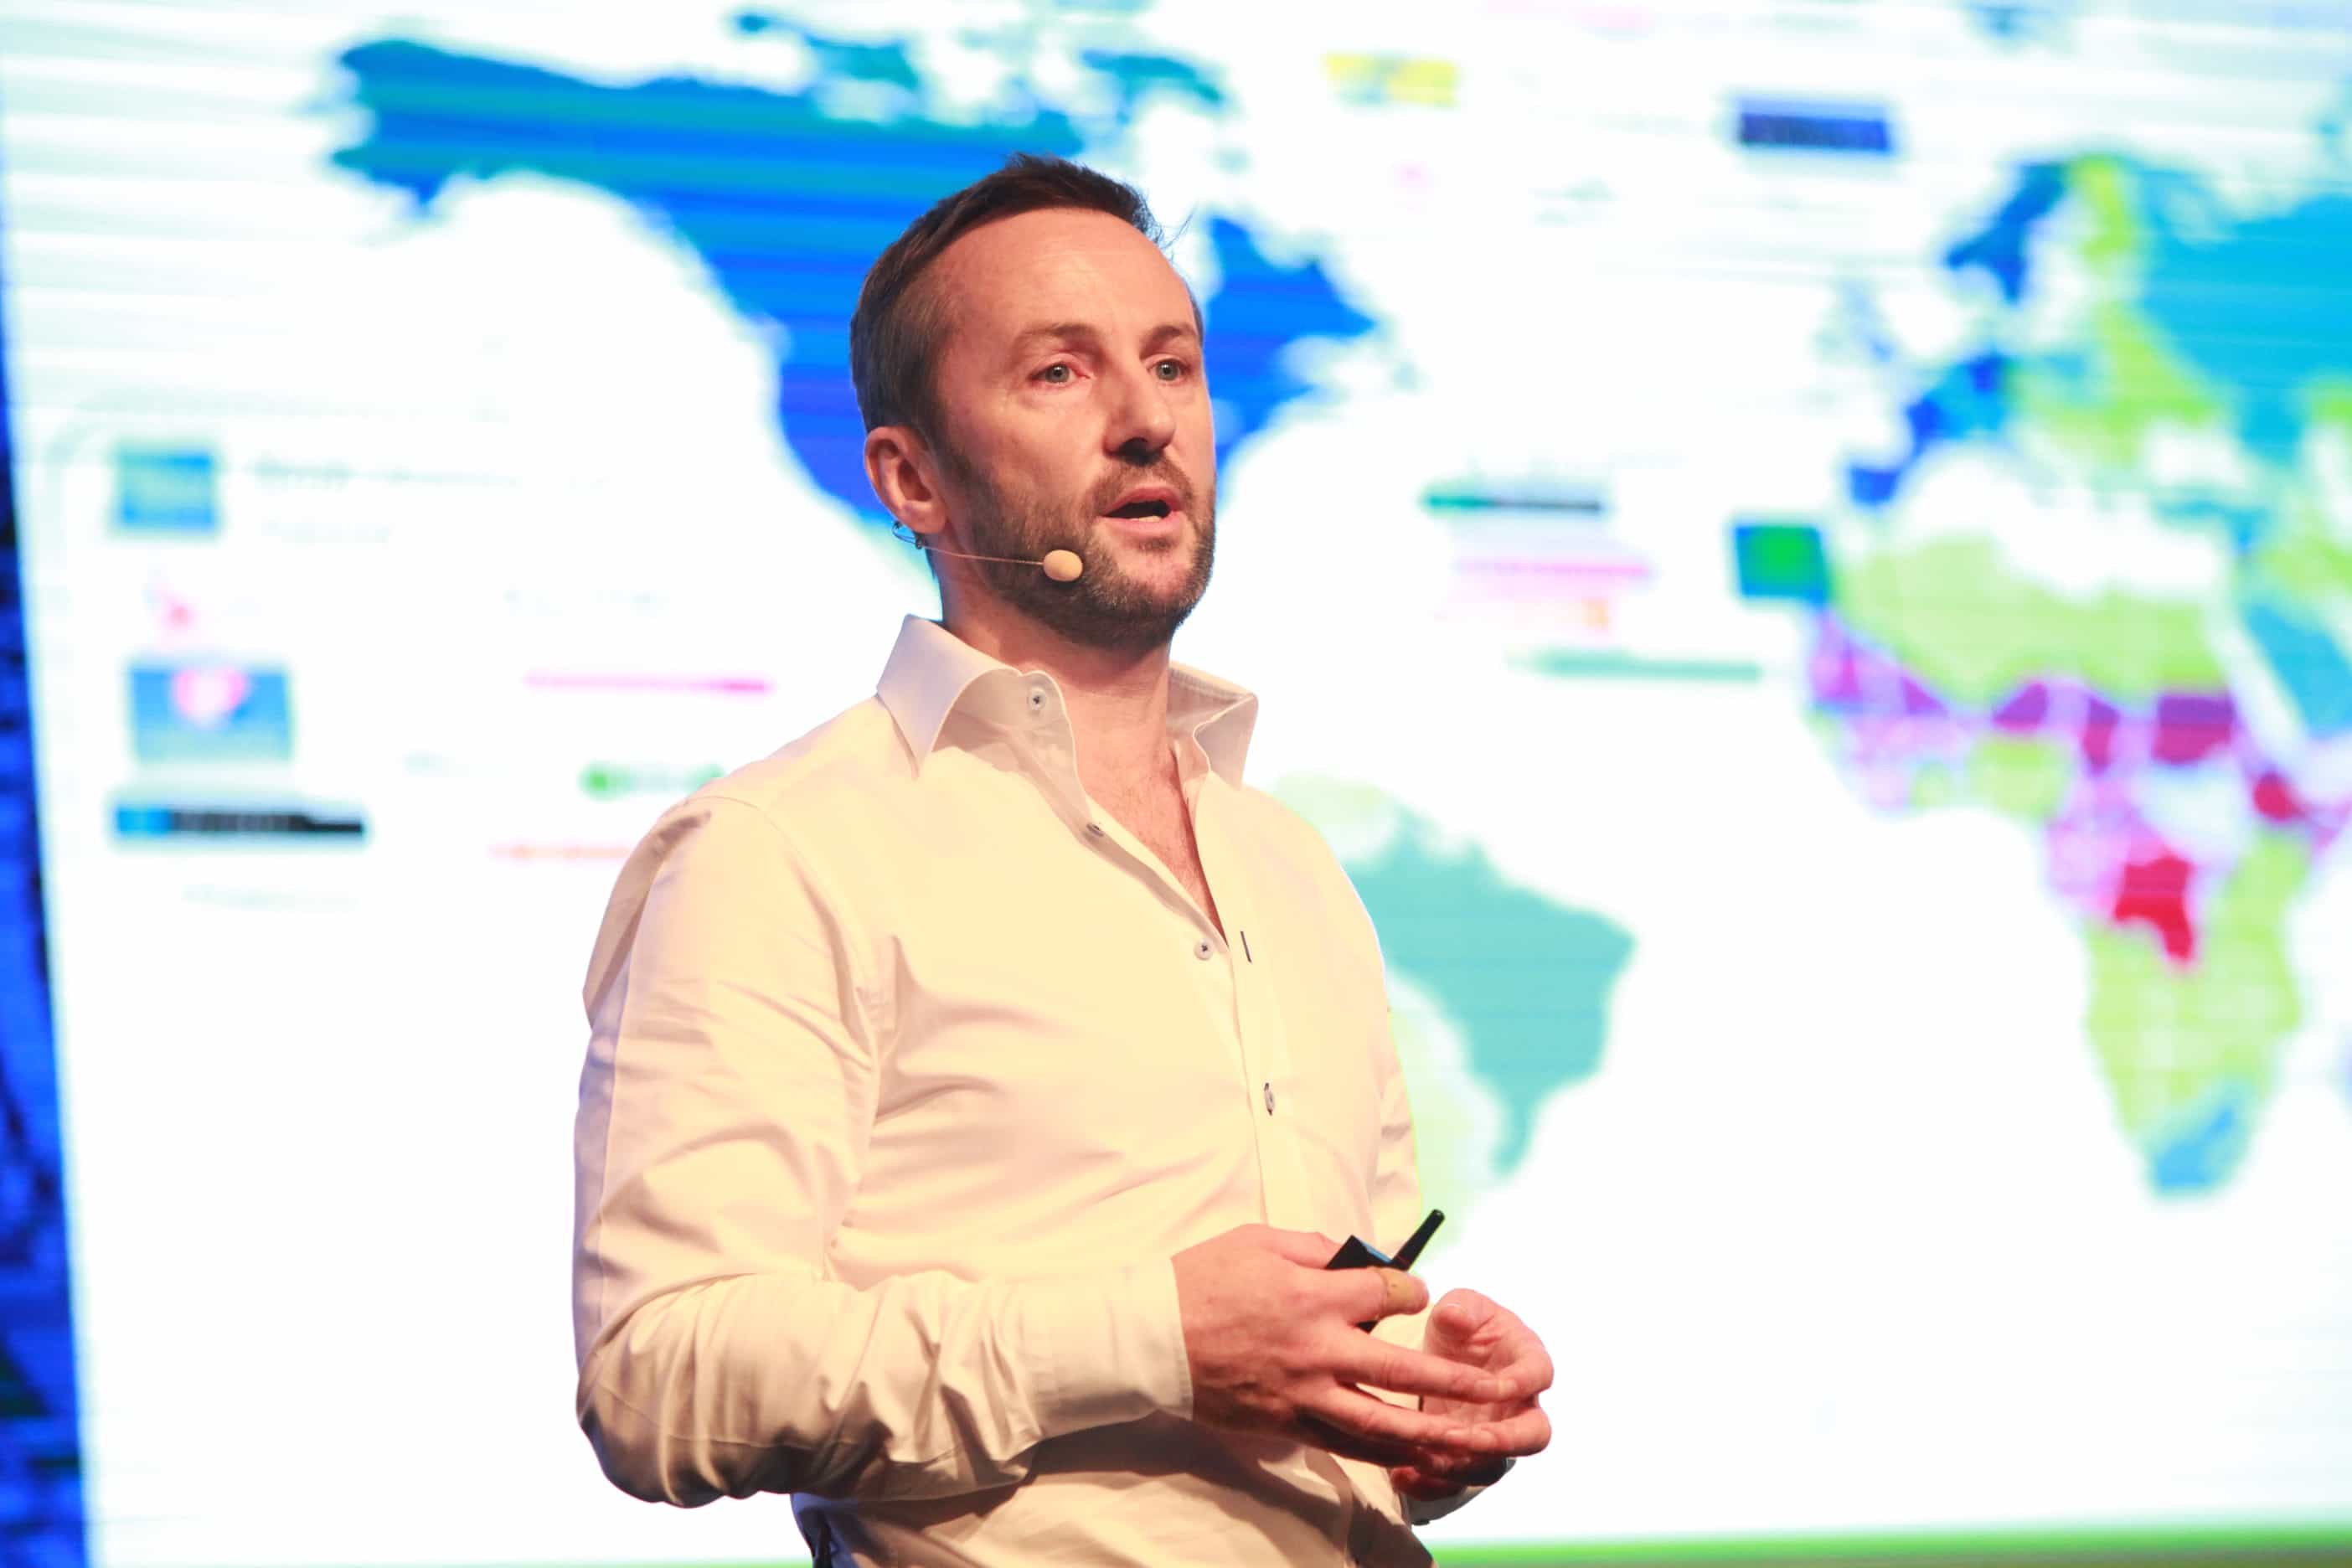
Bobby Healy: Enhance the retailing proposition.
Presenting the results at the WIT Conference, CarTrawler’s co-founder, Bobby Healy, said Asia Pacific airlines had a lot of opportunity to grow ancillary revenues as the 2013 per passenger spend figure of US$13 showed no growth over 2012 while US and European airlines managed to chalk 6% and 14% increase respectively in per passenger spend.
One way to do this, he said, was to increase competitive advantage. He cited the example of Norwegian Airlines which flew 21 million passengers to 133 locations but managed to have car rental booked on Norwegian.com at 1,023 locations. “Passengers travelling with 52 other airlines chose to book their car rental on Norwegian.com, accounting for 19% of all bookings,” he said.
He said airlines can increase ancillaries without sacrificing the customer experience by enhancing the retailing proposition. He cited this example of “the Ariely test” – the Economist offered an online subscription for US$56 and an online + print subscription for US$125. “The Economist’s marketers offered us a no-brainer: relative to the print-only option, the print-and-Internet option looks clearly superior,” quoting Dan Ariely.
With low cost airlines now accounting for 48% of capacity in South East Asia and 28.7% of traffic at Changi airport, it is clear the growth in low cost airlines will push the growth in ancillaries as well.
Some tactics of “air-tailing” in Asia
Overall, we see different tactics emerging in APAC as regional airlines seek to grow their overall revenue pie with definitive brand and country market nuances.

The airline session at WIT 2014
Spencer Lee, head of commercial, AirAsia, suggesting maturity from the strongest LCC group in the region, commented that airlines need to think like a retailer and present relevant purchase opportunities without annoying the customer – that is “to present not so much a service, but an opportunity”.
His statement shows that there is a move away from the more blatant “in your face” service unbundling that has been the characteristic of the ultra LCC airlines like Ryanair.
For the AirAsia Expedia joint venture, cross selling ancillaries is a somewhat easy and complementary model as they’re able to share data and customers with each other, and not just from within this region.
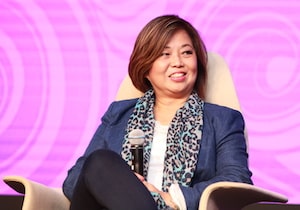
Kathleen Tan: “Element of fear” and “value-add power” urge consumer to book now,
In agreement with Healy’s suggestion that “fear” works well in getting customers to buy more online, Kathleen Tan, CEO of AirAsia Expedia, said that Expedia’s blend of “an element of fear” and “value-add power” works in urging the consumer to book now, as the “hurry – there are only 2 seats left” pop-up message suggests they won’t get it any better than this.
Similarly, when offering customers a “No Insurance” choice, an airline can ask the question – “are you really prepared to take the risk?” – and that often succeeds in converting.
From the fast growing Middle East region, Emirates (EK) as a premium brand, has a very different take on this and currently does not sell ancillary products.
Sameer Poonja says it has ‘listened to its customers’ and places value on their overall product experience. EK has decided not to unbundle baggage, food and entertainment from its base ticket offering. It believes that the differentiated superior experience across all cabins coupled with no unbundling is what its customers really want.
But are GDSes responding to the challenge? A comment sent in by Azran Osman Rani, CEO of AirAsia X, “GDSs are waking up, but a lot more effort needs to be put in, to enable full functional ability to sell LCC inventory on connecting sectors. Without mentioning names, we have some GDSs that today are capable to selling our ‘fly-thru’ sectors and other GDSs that can only sell our basic point-to-point routes. The latter will be disadvantaged. Additionally, full ability to sell our customised ancillary services remains a big gap for all GDSs.”
On the agency distribution front, Travelport’s Mark Meehan indicated that there is a clear message from the intermediary community. In a company-sponsored survey, 84% of Galileo’s agents suggest they too want to sell ancillaries. In response to Osman Rani’s comments that GDS’s could do better at helping sell ancillaries, he said the company has modified its core system to accommodate a range of agency product and content – baggage, food, entertainment, etc, through a new Merchandising Platform – and in fact, had just signed an agreement with AirAsia.
Lee said it was still too early to gauge the results but that the airline believed in collaboration for mutual benefit.
A lot of opportunity for APAC airlines to grow ancillary revenues. (Image credit: Spectral-Design/iStock)
Many low cost airlines are hoping to emulate Easyjet’s experience where its presence in the GDS has increased yields by making the former LCC available for corporate bookings.
Healy has one final piece of advice echoing perhaps a shift in the market. ‘Think like a retailer, but do it without annoying the customer”. Even the GDS’s are changing their previously intransigent position and are moving to accommodate both LCCs and the sale of ancillary products.
Full Service airlines are attempting to emulate the LCC model and achieve the same yields, setting the stage for more direct conflict between them. Regardless of LCC or Full Service airline, OTA or metasearch, corporate or leisure travel, East or West, ancillaries should be a relatively easy product to sell. It’s time the technology, direct and indirect, stepped up and made this easier for the consumer.
• Gill Hazel can be contacted consult@travel strategy, Sydney, Australia