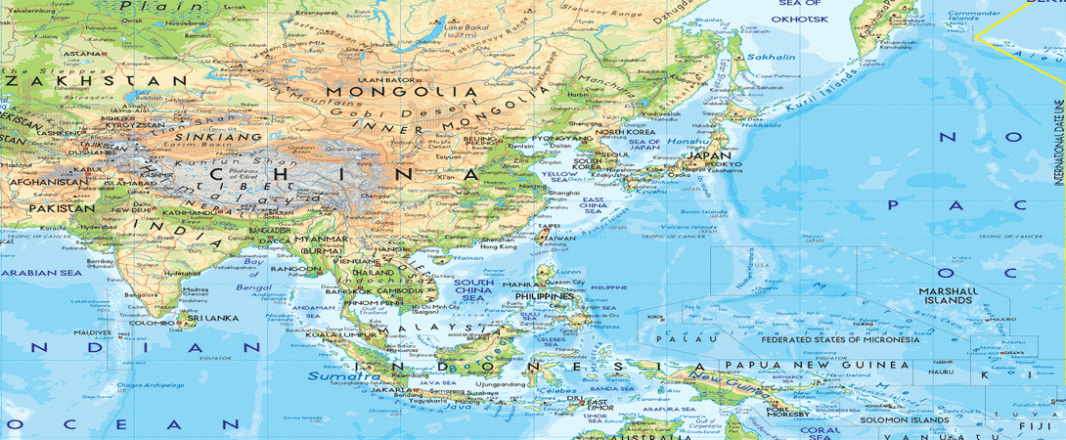

PhoCusWright’s Asia Pacific Online Travel Overview Fourth Edition, due out this week, values the size of the market at US$53 billion or 21% of the total travel market.
“That’s half the size of the US and European market so you can no longer say it’s emerging. It’s already big and it’s going to get bigger,” Douglas Quinby (Ieft), who has been instrumental in putting together the report, told WIT in a call from the US tonight.
The share shift to online is also impressive, said Quinby. “Online travel is growing faster than total travel. In 2008, its share of total travel was just 15% and we project it to reach 24% by 2012.”
Quinby said APAC had been the saving grace of the global travel economy in the last two years. Driven by India and China, online travel, in particular, is really racking ahead, he said.
He said there were two different stories in APAC. One, the matured markets of Australia, New Zealand and Japan which behave like markets in Europe and North America where online penetration is about a third or higher.
“At 34-35%, it’s a tipping point and the market behaves more or less like total travel. So in 2009 with the recession, online travel in Australia and Japan declined along with the travel market.”
However in the emerging markets, such as India, China, Malaysia or Indonesia, where online penetration is lower, online travel is growing ahead of the market.
Even within India and China, the differences are striking, said Quinby.
“China, interestingly, is the second largest travel market in APAC after Japan, but online travel is relatively small, at 7% but growing rapidly. There are some structural factors inhibiting the growth of online such as the inability to purchase rail tickets and restrictions on third parties to access Travelsky’s IBE.
“In the hotel market, there isn’t the widespread use of property management systems and CRSs and you can see from the big OTAs like Ctrip and Elong, the majority of bookings is still done offline.”
India, which is well on its way to becoming a matured market with 21% penetration in online travel, is “growing like a bat out of hell”, said Quinby. “Not just online but the total travel market is growing and really, the India story is just beginning.”
He noted the unique dynamic in India where airlines, in particular, low cost airlines have very strong relationships with the OTAs. “Most of their online sales are coming from the OTAs and that’s where Indian travellers are shopping.”
He said this was generally the trend in most parts of Asia where “we are definitely seeing consumers booking with OTAs rather than supplier direct”.
There are exceptions of course like Malaysia or Singapore where “there are real standout suppliers who get direct business”, AirAsia being a case in point.
“It’s interesting to see the joint venture between Expedia and AirAsia which seems to be an acknowledgement of the limits of supplier direct relationships and also the limits of global brands in expanding in Asia,” said Quinby.
To him, it’s this interplay between intermediary and supplier that’s most striking about Asia Pacific. “Consumers are comfortable with booking with intermediaries and as consumer behaviour shifts online, there is a strong role for intermediaries.
“Traditional travel agencies in most of Asia have been a little slow in coming online and they need to develop strategies. The shift is definitely happening.”
He noted hybrid players like Flight Centre and House of Travel which have developed formidable online plays.
Another striking area identified in the research is the huge opportunity in the hotel segment which is so fragmented. “The hotel opportunity is just beginning and there’s a lot of focus among online travel agencies in this area. Wherever you’ve got fragmentation, there’s opportunity for aggregation.”
He said, “This is the most dynamic segment and with the joint venture between Expedia and AirAsia, we may see the beginning of companies really exploring the opportunities for online and dynamic packaging.”