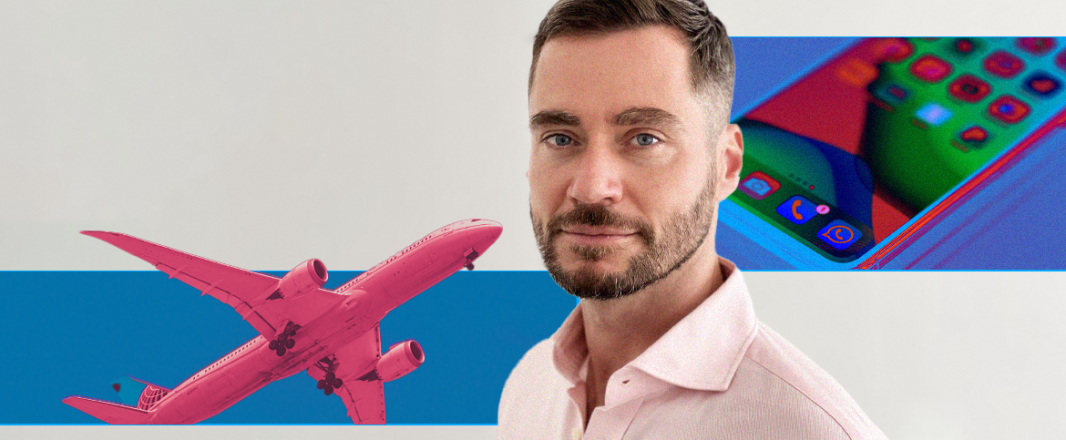
After having spent 20 years of his career on the airline side of the fence, with carriers such as Jetstar, Qantas and Scandinavian Airlines, Clive Ashmore Butler felt it was time to see airline distribution from another perspective. He joined Atlas, the technology platform that connects travel sellers and low-cost carriers, earlier this year as Chief Customer Officer.
Ashmore Butler, who was with Jetstar, both in Melbourne and Singapore, said, “What’s happening in airline distribution is fascinating, with an ever-evolving landscape challenging airlines’ ability to adapt while also providing opportunities to access new markets and customer segments. Atlas’ technology can help airlines navigate this complex landscape”.
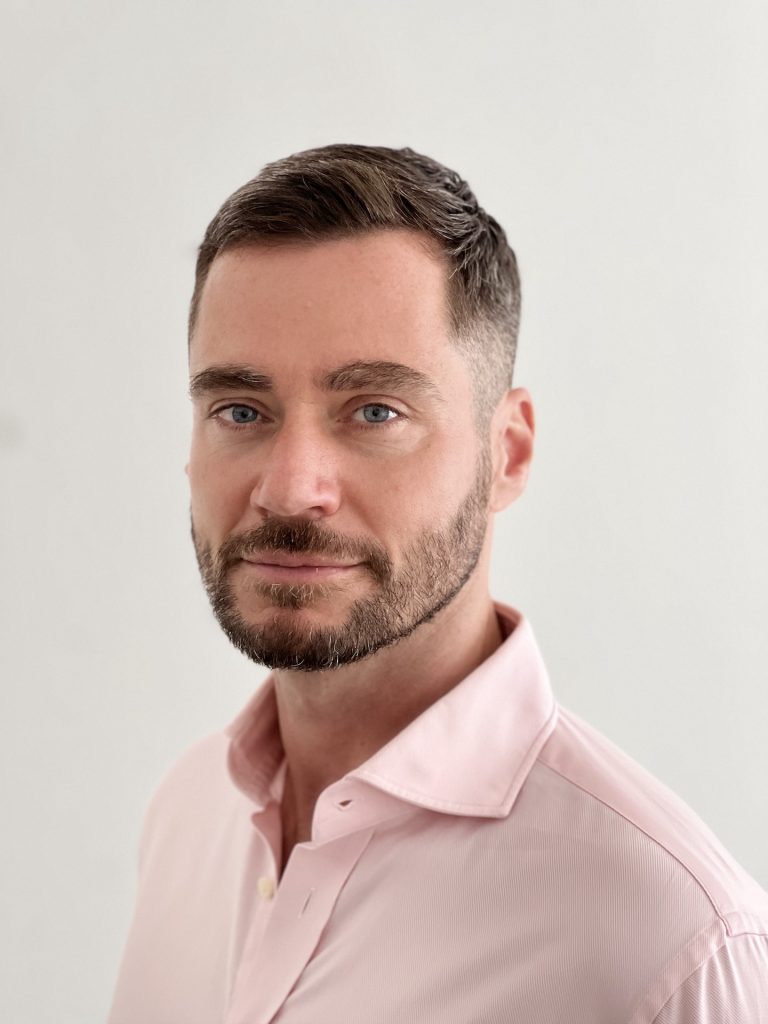
Ashmore Butler on the growth of OTAs and meta-searches: “The bigger players have so much money to invest in retail which airlines don’t have the ability to match.”
Ashmore Butler, who’s been charged with supporting customer growth and building partnerships with travel sellers and low-cost carriers, cited three trends that were shaking up the low-cost market.
One, the continued growth of the OTAs and meta-searches. “The bigger players have so much money to invest in retail which airlines don’t have the ability to match. Travelers also like them because they are more neutral in proposition. It’s exciting to see that growth because it brings more opportunities for the ecosystem.”
Two, the continued adoption and development of new tech and new players. “The rise of superapps is interesting to watch. Grab, TikTok – you can imagine them selling air with their following and customer loyalty.”
Three, the changes and developments happening in the indirect ecosystem with players like Atlas offering new tech solutions to travel businesses across the spectrum to empower them to sell competitive low-cost fares and content.
“Airlines could transform by working closely with players such as Atlas to develop deeper partnerships and create solutions together.”
Ashmore Butler of course concedes that when he was working on the airline side, his priority was to drive direct sales while ensuring that any indirect sales generated incremental revenue to the airline. However, he said, things are changing.
“It is certainly easier for top tier carriers to drive direct business but there is so much transformation and development in the indirect space now, so much more competition for the consumer, that it is no longer as easy as directing consumers to your website. You have to engage and participate with indirect players, especially outside your home market where your brand is not as known, and as you expand your international network and distribution reach.
“OTAs are investing so much in air distribution capabilities and it’s not going to be easy to compete with them. Then there is metasearch which surfaces the most competitive fares. And on top of that, you have emerging channels – superapps like Grab, or social platforms like TikTok. Any of these invest heavily in the airline distribution space with their huge following of customers. You need to be aware of all these new channels and be open to exploring collaborations and partnerships.”
Ashmore Butler said post-pandemic, the indirect eco-system is as strong as it was, and if anything, it gets stronger with more players entering this space. “Of course, airlines have to prioritise direct sales but you also have to navigate new technology and channels and have capabilities to manage them.”
Speaking from personal experience, he said, “You need direct at home, but outside home, you need a mix of direct and indirect. When you are working in the Australian market, for example, you can miss out on emerging trends outside home. Most of us struggled to understand the distribution landscape in China, for example. It can take two to three years to get up to speed, by which time your competitors are ahead of you.”
He said that Atlas, which will deliver connectivity to 200 low-cost carriers was assessing how best to work with smaller travel agents – to give them access to competitive low-cost content and fares – and was considering a pilot proposition for agencies with less than $1m turnover.
“It is difficult for these smaller agencies to compete with the likes of Expedia, but their strength is that they are niche-focused so can play well within their specific segment. Access to superior content is just as relevant for them as it is for the large players.”